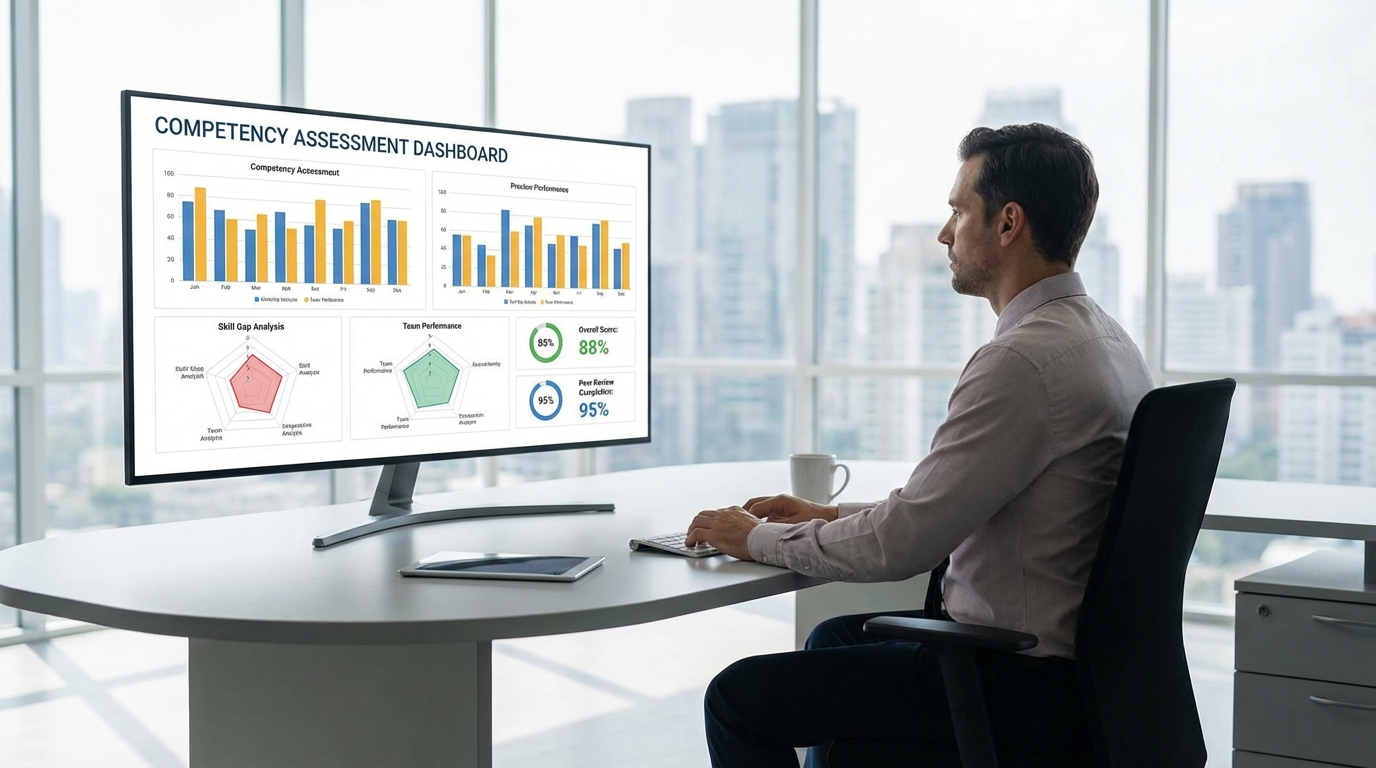
Banking and insurance occupy a peculiar position in the customer relations landscape. Unlike public transport, where the customer wants a ticket or information, or retail, where they want to buy something, the banking customer usually comes in to talk about their money. That is an intimate act, loaded with emotion: fear of making the wrong call, suspicion about fees, anxiety about borrowing or saving decisions.
The adviser therefore manages a trust relationship that is unusually fragile. A clumsily worded recommendation, a whiff of sales pressure, a misread need — and the customer closes the account, leaves a one-star review, or files a complaint with the regulator.
The sector is also mid-transformation: services are moving to apps, chat and video; branch networks are shrinking; and regulatory requirements keep tightening (IDD, GDPR, anti-money-laundering, PSD2). Advisers have to keep climbing the skill ladder simply to stay relevant against the digital alternatives — fintechs, neobanks and online brokers.
Core responsibilities:
Typical profile: trained in financial products, often with an insurance qualification, commercially capable, patient, a genuine listener, geographically mobile.
Relational context: a wide mix of customers — young professionals, retirees, business owners — with requests ranging from trivial to complex, under moderate to heavy commercial targets.
Core responsibilities:
Typical profile: business experience, able to read a P&L, highly autonomous, well networked.
Relational context: customers who are experts in their own field but want complementary expertise; more formal than retail, with larger sums at stake.
Core responsibilities:
Typical profile: highly qualified, significant experience, strong commercial and networking ability, comfortable with financial modelling.
Relational context: demanding clients, sensitive to performance and confidentiality, in relationships that often run a decade or more.
Core responsibilities:
Typical profile: versatile, fluent in the CRM and banking tools, able to work under time pressure, genuinely multitasking — listening, typing, advising and resolving at once.
Relational context: remote customers, requests from simple to complex, heavy time pressure, and satisfaction driven directly by speed and clarity.
Core responsibilities:
Typical profile: experienced, formerly an adviser, strong on leadership and communication, comfortable steering both commercial and operational KPIs.
What is at stake: customers expect genuine expertise, the ability to explain complex products, and confidence that the adviser knows the rules.
Required: full command of the product range; understanding of the regulatory frame — IDD disclosure duties, GDPR, anti-money-laundering, PSD2; the ability to translate complexity into plain language; and continuous updating as products and rules change.
In practice: a customer asks which loan protection policy you would recommend. The adviser has to know the disclosure obligations, explain the differences between cover, excesses and waiting periods without jargon, and then propose what actually fits the customer's risk profile.
What is at stake: banking customers are afraid of being sold something they do not need. Trust rests on visible proof that the adviser is listening.
Required: structured questioning to establish the real situation; reformulation to confirm understanding; an absence of judgement when personal circumstances are difficult; and prioritisation — deal with the primary need before identifying anything secondary.
In practice: a customer says they want to invest a lump sum. The wrong answer is to open with the best-performing product. The right sequence is to ask over what horizon the money is needed, whether it is earmarked for something specific, what wrappers they already hold, and what their tolerance for loss actually is — and only then to recommend.
What is at stake: the model has shifted from selling products to selling solutions. That is a different posture entirely: the customer sits at the centre, not the product.
Required: a complete diagnosis before any recommendation; an explicit bridge from need to solution — based on what you have told me, here is what I suggest; objection handling without defensiveness; and post-sale follow-up to check the solution is working.
In practice: the customer objects that the fees are too high. A weak adviser defends. A strong one converts the objection into a comparison: what the fee costs in absolute terms per year, what it buys, how it sits against the market, and what a lower-cost alternative would mean in reduced return or reduced cover. The customer then makes an informed choice — which is precisely what the regulation intends.
What is at stake: customers disclose income, debt, family problems and fears. Those conversations have to be handled as human exchanges, not data collection.
Required: warmth in the face of anxiety; neutrality when the situation is genuinely difficult, such as over-indebtedness or a separation affecting finances; the ability to offer practical help; and absolute confidentiality.
In practice: a customer arrives visibly stressed about a large mortgage and afraid they will not be able to repay it. The adviser listens without judgement, normalises the fear, then works through real affordability — term, rate, protection — and, if the numbers do not hold, reshapes the amount rather than pushing the application through.
What is at stake: the regulatory perimeter keeps tightening. A compliance failure is a serious legal exposure for the institution and, in some cases, for the adviser personally.
Required: knowledge of the legal obligations; the ability to recognise fraud and laundering signals — abnormal amounts, a profile that does not fit, urgency without documentation; disciplined documentation of requests and rationale; and escalation to compliance whenever there is doubt.
In practice: a customer wants to send a large transfer to an overseas account. The adviser asks what it is for, checks whether the beneficiary is established, documents the exchange in the CRM, and escalates if anything about the amount, destination or relationship looks wrong.
What is at stake: banking customers escalate quickly when something goes wrong — a failed transfer, a disputed fee, an investment that underperformed. The adviser's job is to bring the temperature down.
Required: immediate acknowledgement of the frustration; ownership of the problem without either blaming the institution or hiding behind it; a fast, concrete remedy; and documentation so the same failure does not recur.
In practice: a customer is furious about a fee they did not expect. The adviser acknowledges it plainly, investigates on the spot, and — if the charge was wrong — reverses it and says so, rather than explaining the tariff schedule.
Situation: the rules change quickly and penalties for non-compliance have risen sharply across European regulators.
Impact: advisers need regular training and regular assessment. One-off training no longer discharges the obligation.
Training response: short, frequent modules — fifteen minutes a month on what has changed — with annual certification.
Situation: banks set sales targets. They must simultaneously respect suitability rules and customer rights.
Impact: advisers are caught between the two, and the failure mode is a mis-sold product, an unhappy customer, a complaint and a fine.
Training response: teach advisory selling rather than aggressive selling, and demonstrate with real numbers that trust generates more lifetime revenue than a forced sale.
Situation: customers check balances, make transfers and ask questions in-app without ever visiting a branch.
Impact: if an adviser only offers what the app already does, the role has no reason to exist.
Training response: move advisers up the value chain — portfolio analysis, tax efficiency, retirement, succession. The adviser has to become an expert rather than an administrator.
Situation: advisers are worn down by stress, commercial pressure and rising complexity. Attrition runs high in several markets.
Impact: expensive re-training, degraded service quality, and the loss of long-standing customers who were loyal to a person rather than a brand.
Training response: preparation that actually builds confidence. Rehearsing the hard conversation in advance reduces the stress of having it for real — and confident advisers stay longer.
Situation: a young couple on a combined income want to buy a property well above it. They are afraid of the repayments.
Skills rehearsed: listening to the anxiety rather than the numbers; assessing genuine affordability; presenting a reassuring but honest structure; and, where necessary, resizing the project or advising them to wait.
Situation: a retiree with modest income and a moderate portfolio wants to put a large share into volatile assets because a neighbour made money.
Skills rehearsed: listening without condescension; questioning the horizon and the tolerance for loss; assessing the real risk profile; and proposing a blend that respects the customer's appetite without exposing them to a loss they cannot absorb.
Situation: the customer compares their monthly account charges with a free digital challenger and asks why they should stay.
Skills rehearsed: acknowledging that the question is fair; breaking the charge into what is core service and what is optional; offering a genuine reduction; and, if the customer really only wants basic banking, migrating them to a cheaper product rather than defending the current one.
Situation: an international transfer sent days earlier has not reached the beneficiary, and the customer stands to lose a commercial deal.
Skills rehearsed: immediate acknowledgement of the urgency; a real investigation rather than a reassurance; transparent communication about what is normal and what is not; a committed callback time; and compensation where the fault was internal.
Situation: a long-standing retailer wants to borrow to refurbish their premises, has never borrowed before, and is visibly unsure.
Skills rehearsed: reframing trust as capacity — the question is not whether the bank likes them but what the accounts support; a serious review of turnover, margin and sector comparison; a clear yes with conditions, or a considered not yet, and here is what would change that rather than a blunt refusal.
Face Up builds AI simulations specific to this sector:
A typical deployment: each adviser completes one seven-minute scenario per week for twelve weeks — mortgage, investment, fee objection, complaint. On our client programmes this has produced a 92% completion rate, an eight-point NPS gain and a six-point improvement in conversion.
If you want to change how advisory conversations run across your branch network, we design the scenarios around your products, your compliance frame and your indicators.
Get in touch at contact@face-up.fr.