
In banking, branch advisers face a contradiction. On one side, ambitious commercial targets: investments, mortgages, insurance. On the other, an increasingly strict regulatory framework: the duty to advise, MiFID II compliance, anti-money-laundering obligations, data protection.
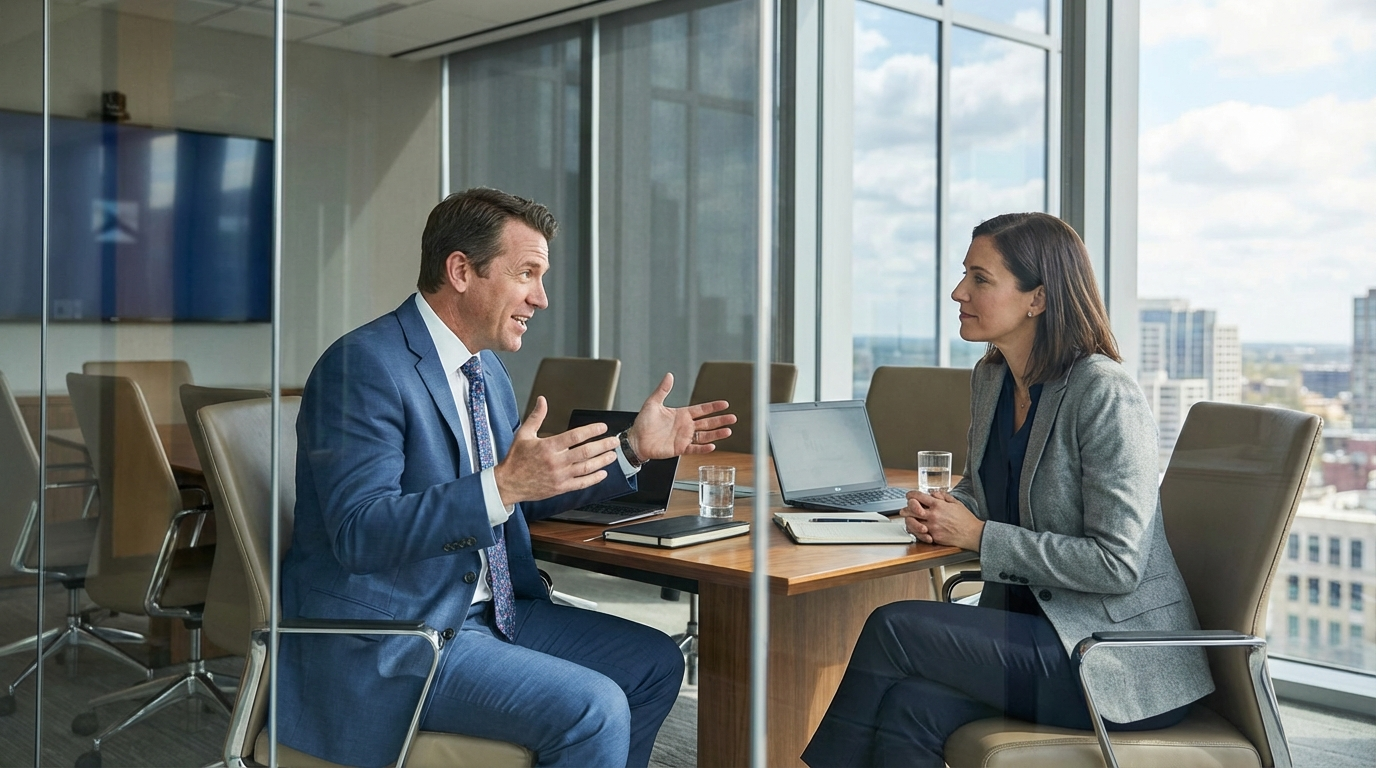
That double bind is what pushed a regional bank (350 advisers, 85 branches) to rethink its approach to customer relationship training. The starting point was clear: compliance training was seen as an administrative obligation, and sales training stayed too theoretical to change what advisers actually did in a client meeting.
The head of learning summed the problem up: "Our advisers spend two days a year in compliance training, then go back to the branch and do exactly what they did before. Not out of bad faith, but because between the theory and a live client meeting there is a chasm."
A cross-referenced audit (mystery shopping plus file review) revealed three areas of weakness:
Insufficient discovery. 62% of advisers spent less than five minutes on the discovery phase before presenting a product. The questions were technical — financial situation, income — but rarely oriented towards the client's life plans. Active listening was being sacrificed to the product pitch.
Undocumented advice. Even when the advice was sound, the regulatory audit trail was thin. 38% of investment files showed gaps in the documentation of the client's risk profile — a serious regulatory exposure.
Handling objections and refusal. Faced with a hesitant client, advisers swung between two extremes: aggressive pushing (with the risk of a mis-sale) or giving up too quickly (a lost opportunity). The ability to handle difficult situations — here, resistance to buying — lacked subtlety.
The bank deployed an AI role-play programme aimed specifically at client-meeting skills. The approach combined conversational practice and regulatory compliance within the same scenarios.
The scenarios were designed to reflect the defining moments of a bank adviser's job:
The first meeting with a new client moving accounts from another bank. A savings and investment discussion with a cautious client hesitating between a cash savings account and a longer-term investment wrapper. A mortgage renegotiation with a client well informed by online comparison sites. The client unhappy about bank charges who threatens to move to a competitor. The vulnerable client — an elderly person, or someone in financial difficulty — where the duty to advise matters most.
Each scenario embedded compliance checkpoints: the adviser had to ask the right questions, document the risk profile, and match the recommendation to the client's profile — all while keeping the conversation natural.
The pathway followed a build-up of core competencies:
Weeks 1-2: mastering client discovery (3 sessions). Weeks 3-4: product argumentation and compliance (3 sessions). Weeks 5-6: handling objections and negotiating (3 sessions). Weeks 7-8: complex scenarios and vulnerable clients (3 sessions).
The five-minute sessions were followed by structured debriefs, with skills assessment against a dual scorecard: relationship quality and regulatory compliance.
+28% close rate on savings and insurance products. The biggest improvement came in investment meetings: trained advisers spent an average of 12 minutes on discovery, against five before, which produced better targeted recommendations and a higher acceptance rate.
+45% regulatory compliance on file documentation. The share of compliant files rose from 62% to 90%, cutting regulatory exposure sharply. Internal controls confirmed a qualitative improvement in documented risk profiles.
-35% client complaints relating to inadequate advice. Clients dealt with by trained advisers reported feeling better informed and more confident in the recommendations they received.
340% ROI calculated over 12 months, taking in the additional revenue generated, the reduction in non-compliance costs and the saving on classroom training. For a detailed look at the methodology, see our guide to calculating the ROI of training programmes.
Traditionally, compliance training and sales training live in separate worlds. Here, every scenario required the adviser to be commercially effective and compliant at the same time. That integration helped advisers see that compliance is not a brake on selling but a lever for client trust.
The AI avatars were calibrated on real client profiles: the busy senior executive who wants to "get on with it", the wary retiree burnt by a bad investment, the young first-time buyers overwhelmed by mortgage complexity. Communication had to adapt to each profile.
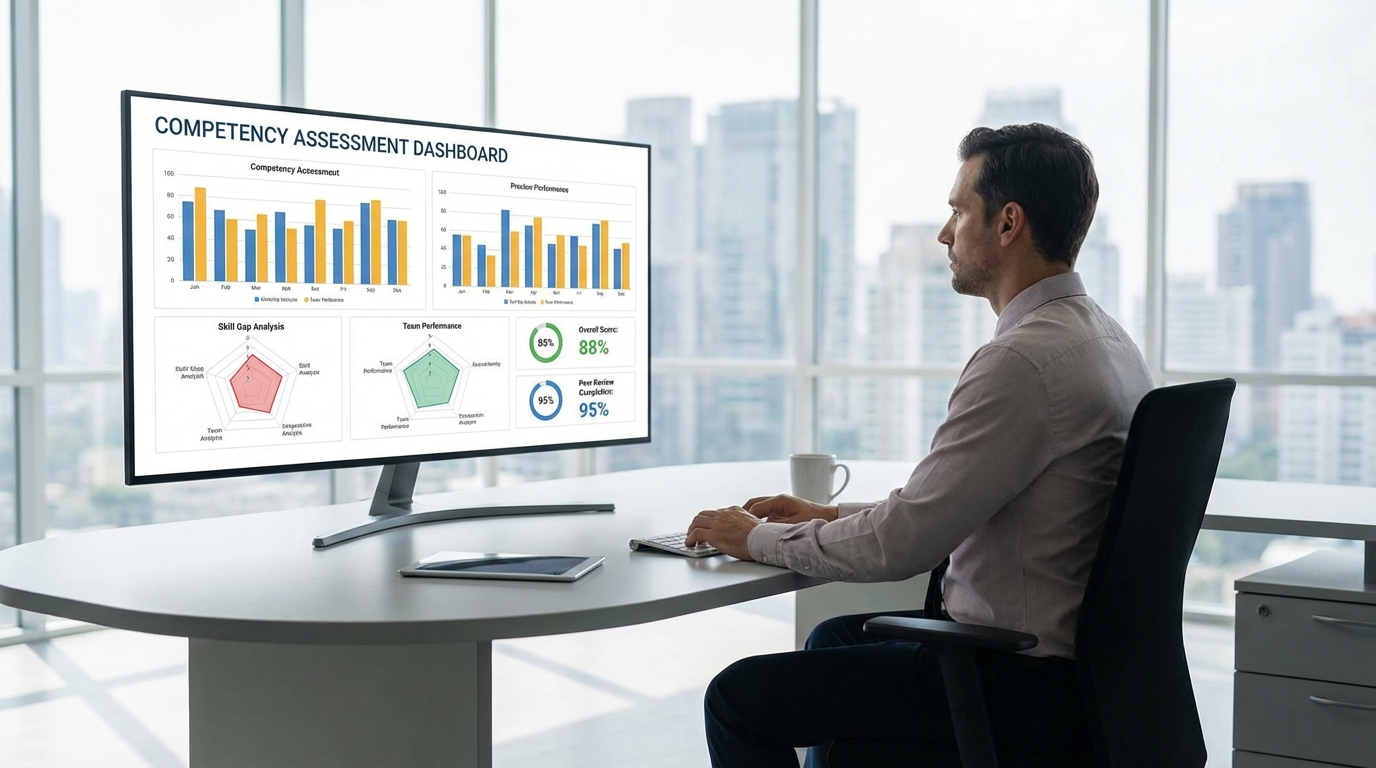
Branch managers had dashboards for each adviser: sessions completed, progression on each competency, points to watch. That made targeted debriefs possible in weekly team meetings.
The microlearning format — five minutes on a smartphone between two appointments — removed the main barrier to training: time. 88% of advisers completed the whole programme, an exceptional completion rate compared with the 45% typically seen on traditional e-learning modules.
This case study confirms that learning through practice suits banking particularly well, because the quality of the client relationship feeds directly into both revenue and compliance.
Three principles stand out. First, never separate sales training from compliance training — they are two faces of the same competency. Second, favour spaced repetition on the situations that matter most over intensive annual courses. Third, equip managers so they can turn training data into individual coaching.
Banking is deep in digital transformation, and the in-branch relationship remains a decisive advantage for regional banks. Investing in the quality of that relationship is investing in retention and in compliance — the two pillars of long-term viability.
Want to run a similar programme with your advisers? Discover Face Up and explore our ready-built banking scenarios.